Sovereignty law not responsible for Uganda shilling’s fall – BoU
Bank of Uganda governor Michael Atingi-Ego has dismissed suggestions that the Protection of Sovereignty Act, 2026, may have contributed to the recent depreciation of the shilling, attributing the currency’s weakness instead to a widening current account deficit and reduced portfolio investment inflows. The Protection of Sovereignty Act, which President Yoweri Museveni signed into law in […] The post Sovereignty law not responsible for Uganda shilling’s fall – BoU appeared first on The Observer Media Ltd.
 Black News
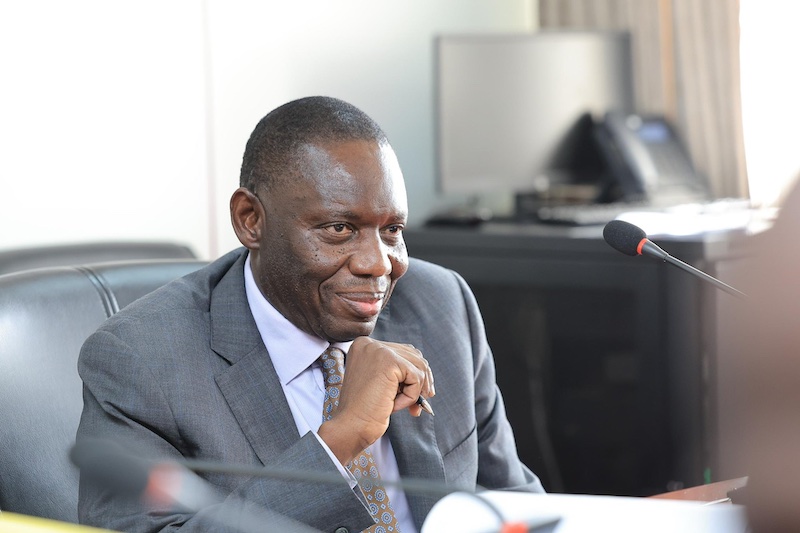

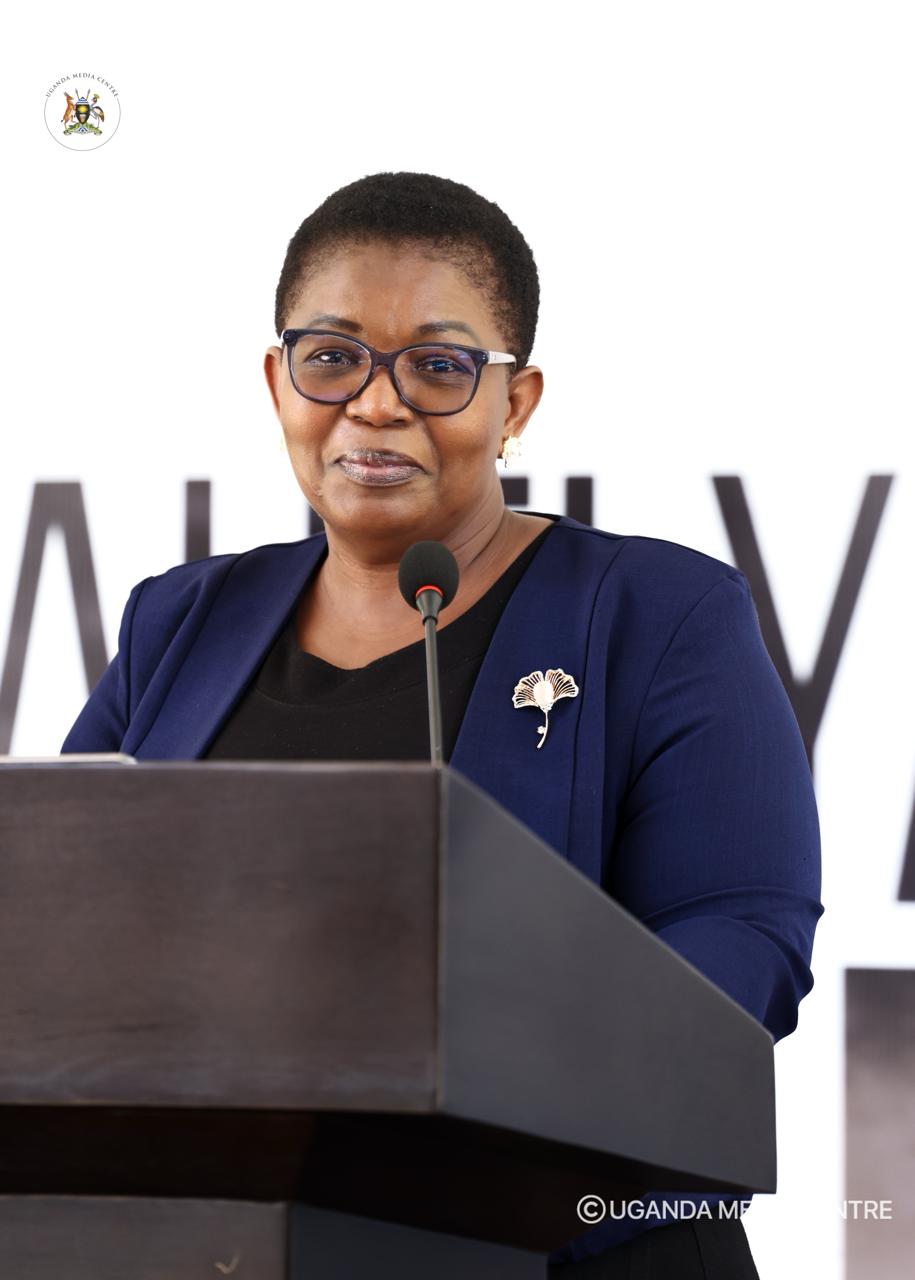
Bank of Uganda governor Michael Atingi-Ego has dismissed suggestions that the Protection of Sovereignty Act, 2026, may have contributed to the recent depreciation of the shilling, attributing the currency’s weakness instead to a widening current account deficit and reduced portfolio investment inflows.
The Protection of Sovereignty Act, which President Yoweri Museveni signed into law in May after Parliament revised some of its contested provisions, regulates the activities and foreign funding of people and organisations acting in the interests of foreign entities.
During a press conference on Wednesday, a participant raised concerns about reports that more than $200 million had flowed out of Uganda in the preceding two weeks, amid growing pressure on the shilling.
The law had earlier attracted concern from the Bank of Uganda over the potential impact of restrictions on foreign investment, remittances and other cross-border financial flows.
Responding to journalists following the central bank’s decision to raise the Central Bank Rate (CBR) by 2.25 percentage points, from 9.75 per cent to 12 per cent, Atingi-Ego said the depreciation was primarily driven by deteriorating external balances. The rate increase was intended to contain inflationary pressures and limit further depreciation of the currency.
The governor said Uganda’s external payments position had deteriorated, with the goods trade deficit widening to $2.8 billion from $2.4 billion, while the services deficit increased to $3.3 billion from $2.2 billion in the 12 months to August 2026.
He attributed the deterioration in the services account partly to tourism losses associated with Ebola. The primary income deficit, which includes interest payments on government debt and other income payments to non-residents, also increased to $1.7 billion from $1.4 billion.
Responding to a question about whether uncertainty surrounding the Sovereignty Bill and restrictions on civil society organisations could have discouraged foreign investors and development partners, Atingi-Ego rejected the suggestion that the law explained the shilling’s depreciation.
“What I would want to say is that this does not in any way explain what the Sovereignty Bill did. This explains the deterioration in the current account balance, explaining the depreciation in the currency,” he said.
The governor did not directly confirm whether more than $200 million had left the economy during the preceding two weeks. He added that the moderation of portfolio investment flows had contributed to further pressure on the shilling.
Atingi-Ego said secondary income, which includes remittances and other transfers, had increased to $3.1 billion from $2.7 billion, providing additional foreign exchange inflows.
He maintained that the depreciation was “purely a balance of payment matter”.
The governor acknowledged that the rate increase could raise borrowing costs and slow economic activity but argued that allowing inflationary pressures to become entrenched would carry greater costs for the economy over the medium and long term.
Dr Adam Mugume, the Bank of Uganda’s executive director for research and policy, said the central bank expected core inflation to rise towards 5.5 per cent to six per cent, creating a risk that price increases would spread across a wider range of goods and services.
He said the policy decision involved a trade-off between controlling inflation and supporting economic growth. Mugume warned that tighter monetary conditions could reduce private-sector credit, push interest rates higher and lower economic growth by at least half a percentage point.
However, he argued that higher interest rates could reduce demand for imports and make Ugandan financial assets more attractive to investors, helping ease pressure on the exchange rate.
“The benefits outweigh the costs that will come in terms of slightly lower economic growth,” Mugume said.
Atingi-Ego said the central bank could not afford to wait until inflation and exchange-rate expectations became firmly entrenched among businesses and consumers.
“It might result into reduced growth, higher loan repayments, particularly if your loan is on a variable rate. But it is better to rein in these variables before they become entrenched, so as to preserve the medium- and long-term stability of the economy,” he said.
The decision presents a difficult choice for businesses and households already facing higher import costs and a weakening shilling. While tighter monetary policy is intended to curb price increases, borrowers could face more expensive credit as commercial banks adjust lending rates.
Debt sustainability
Atingi-Ego also sought to reassure the public about Uganda’s rising public debt and the implications of the shilling’s depreciation for debt servicing.
Responding to a question about whether the increasing cost of servicing public debt was putting pressure on the government’s ability to finance development and essential services, he said the latest debt sustainability analysis, incorporating the most recent currency movements, had not yet been completed.
He explained that debt sustainability assessments consider different scenarios, including exchange-rate shocks, and examine whether these could push debt indicators beyond established thresholds.
“While we have not yet done the most recent analysis based on this currency, I would want to assure you that the indicators suggest that Uganda’s debt is sustainable,” he said.
He added that, as of August, there had been no indication that Uganda’s debt was unsustainable.
A weaker shilling generally increases the domestic-currency cost of servicing external debt denominated in dollars and other foreign currencies. The full effect of the recent depreciation will depend on the currency composition of the debt, the timing of payments and the findings of the updated assessment.
Inflation versus growth
The governor also defended the decision to tighten monetary policy despite concerns that current inflationary pressures originate largely from supply-side shocks, including rising international oil prices and higher food costs.
Responding to a question about whether higher interest rates could undermine the government’s Tenfold Growth Strategy, Atingi-Ego referred to the experience of 2022, when Russia’s invasion of Ukraine and subsequent sanctions disrupted international energy and grain markets.
He said the Bank of Uganda initially observed the effects of higher fuel prices before tightening monetary policy as the increases began spreading across the wider consumer price basket. He argued that a central bank should not ignore a supply shock once it begins generating broader and sustained price increases.
“So, you’re right, it’s supply-side, but we act when it begins to feed into the broader CPI,” he said.
Higher interest rates cannot directly lower international oil prices, shipping costs or the price of imported food. Instead, the central bank’s intervention is intended to limit the extent to which initial price increases spread through transport, production, distribution and other domestic costs.
The government’s growth ambitions depend on investment and expanding production, while tighter credit conditions could raise the cost of financing those activities.
The central bank maintains that containing inflation and limiting exchange-rate volatility are necessary to preserve the conditions for sustained economic growth.
The post Sovereignty law not responsible for Uganda shilling’s fall – BoU appeared first on The Observer Media Ltd.